
Overview: National economic indicators like a 4.2 percent unemployment rate, 3.4 percent CPI inflation, and climbing interest rates fail to tell the entire human story. Disrupted energy shipping routes and supply chain tariffs hit operating budgets and household expenses directly, while aggressive capital spending on AI infrastructure often outpaces internal workforce investment. Because the K-shaped recovery produces vastly divergent financial realities under the same corporate roof, organizational leaders must look beyond headline statistics to prioritize talent mobility, wage equity, and debt sustainability.
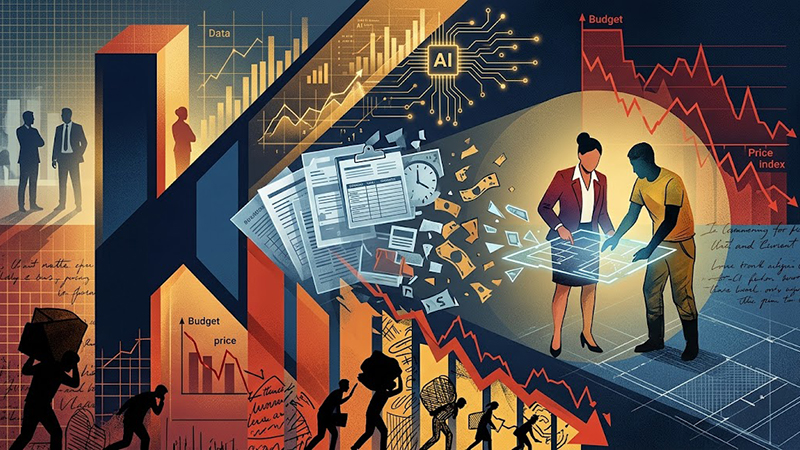
Navigating Global Conflict, AI Workforce Disruption, and the K-Shaped Reality Beyond the Headline Numbers
The Human Side of the Economy: What Leaders Need to Watch Beyond the Headlines
I have the opportunity to attend all kinds of events, and believe it or not, I enjoy a good economic outlook. I am curious about what financial experts are seeing and how those trends connect to our everyday lives. As an inclusion thought leader, I want to understand the people behind the numbers. We all have a stake in these conversations because the economy shapes the decisions we make and the opportunities available to us.
Earlier this spring, I attended a Wintrust leadership session on economics and markets in the age of conflict. I appreciated how the economist made a complicated conversation practical, and I left with plenty to think about. Now that we are in October, I have revisited those takeaways alongside newer information. The core question remains: how do we make thoughtful decisions when the economy keeps shifting?
Economists interpret data and make informed forecasts. Those forecasts can change. My goal is to listen for what the evidence tells us today while preparing for what remains uncertain about tomorrow.
1. Global Conflict Reaches Local Wallets
A conflict overseas can feel far removed from daily life until you fill the gas tank or review an operational invoice. Disrupted oil supplies and maritime shipping routes inevitably introduce costs that filter across the entire economy.
The U.S. Energy Information Administration’s October outlook anticipates constrained Middle East oil flows through the end of 2026. While this is an evolving projection, it explains why energy remains an essential operational cost to monitor. Even with the United States operating as the world’s largest crude oil producer in 2025, domestic output does not insulate businesses or consumers from global price dynamics.
Tariffs belong in this conversation as well. New import duties raise expenses for commercial supply chains, and those costs are often passed downstream to everyday consumers. Leaders need to track where cost pressure originates upstream so they can anticipate when it will reach internal operating budgets.
2. A Steady Unemployment Rate Tells Only Part of the Story
The September jobs report showed unemployment steady at 4.2 percent alongside a preliminary gain of 29,000 payroll jobs. Additionally, the Federal Reserve’s September meeting minutes highlighted low rates of both hiring and layoffs. The reality is far more nuanced than companies simply hiring less or firing more.
For job seekers: Low turnover and slower hiring cycles can feel like professional stagnation.
For business owners: Broader economic uncertainty causes leadership teams to delay approving new requisitions or capital investments.
This is where organizational leaders must look beyond the topline national figures. Examine what is occurring within your specific sector, your regional labor market, and your internal talent pipeline.
3. Balancing AI Infrastructure with Investment in People
Capital expenditure around artificial intelligence extends far beyond software interfaces. It involves massive investments in physical data centers, specialized server hardware, and high-capacity electrical grids. Federal Reserve research published in July described rapid acceleration in AI infrastructure, while noting that measurable improvements in broader worker productivity remain difficult to quantify.
That distinction matters. Capital spending on new technology does not guarantee workforce adoption or equitable gains. For employers, the central question should be straightforward: where is the parallel investment in human capability?
Before assuming certain roles are obsolete, organizations must prioritize training, upskilling, and internal mobility. Providing employees with the resources to develop new skills ensures teams can transition into emerging opportunities. Technological efficiency requires a clear, human-centered talent strategy.
4. The Human Reality of a K-Shaped Economy
The term “K-shaped economy” describes divergent financial trajectories among different segments of the population. Research from the New York Federal Reserve showed that higher-income households have driven a disproportionate share of recent retail spending growth. Aggregate consumer resilience can easily mask severe financial strain in lower- and middle-income brackets.
Meanwhile, the August Consumer Price Index reported an annual inflation rate of 3.4 percent. National price indices do not capture what an individual household feels when paying for everyday essentials like housing, utilities, and groceries.
Within any organization, colleagues working under the same roof often experience vastly different financial realities. Inclusive leadership requires recognizing these disparities when designing compensation structures, healthcare benefits, and career pathways.
5. Navigating Interest Rates, Capital Costs, and Debt
In September, the Federal Reserve adjusted its policy rate target to 3.75 to 4.00 percent, citing persistent inflation pressures. This serves as a clear reminder for organizations and households to stress-test their debt service assumptions. Furthermore, global central banks must navigate their own domestic pressures, meaning monetary policy will not move uniformly across international borders.
When discussing national debt, leaders should be cautious about assuming economic growth alone will resolve fiscal imbalances. Expansion matters, but so do borrowing rates, public expenditures, and tax revenues. At both the business and household level, sustainability comes down to three practical questions:
- What do we currently owe?
- What does that capital cost to service over time?
- What flexibility do we have to absorb unexpected shifts?
Moving Forward with Financial Literacy
I am not an economist. I share these observations because economic literacy directly influences how we lead teams and build sustainable organizations.
You do not need to track every intraday market fluctuation to stay informed. Focus on the indicators that directly intersect with your mission, your community, and your household. Identify three or four relevant economic signals, monitor them consistently, and ask questions when something appears misaligned. Developing a grounded view of the macroeconomic landscape gives all of us the clarity needed to navigate future opportunities.
Pam McElvane, CEO, Author & Publisher, Promena Media
CEO | Master Coach | Board Governance Expert | Data Scientist | Strategist | Publisher
Pamela McElvane, MBA, MA, MCPC, is the CEO and founder of P&L Group, Ltd which has 3 key brands: Promena, 3I Research Institute & Diversity Learning Solutions, headquartered in Chicago, IL. Ms. McElvane has spent more than 25 years working with large and midsize companies providing insights and best practices, leadership and executive coaching, strategy, and organizational management.
About Promena (A P&L Group Brand)
Promena.Set the Standard (previously Diversity MBA) is a media, leadership, learning, research, and insights company dedicated to setting the standard for inclusion, equity, and performance. Through data-driven benchmarks, executive education, and thought leadership, Promena helps organizations turn inclusion from aspiration into a measurable business capability.
About Promena Insights
Promena Insights is the research and analytics division of Promena. It develops proprietary indices, benchmarks, and frameworks—including the Inclusive Leadership Index™ (ILI) and the Industry Inclusion Index (I³)—to measure inclusion maturity and guide evidence-based strategy for organizations and industries.
Contact for public speaking, coaching and leadership training opportunities:
833-362-2100 ext. 700 (Main) | pam@promenasetthestandard.com
#EconomicOutlook #WorkforceDevelopment #InclusiveLeadership