
Overview: Smart truckers are replacing rigid 401(k)s with Indexed Universal Life (IUL) insurance because it provides lifelong family protection alongside a tax-advantaged cash value account. Unlike traditional retirement plans that penalize early withdrawals, a properly structured IUL allows commercial drivers to borrow against their own policy tax-free for truck repairs, fleet expansion, or slow freight seasons while protecting their principal with a zero percent market floor.
Josiah Farrow for Unsplash
How owner-operators and commercial drivers use Indexed Universal Life policies to fund truck repairs, scale fleets, and protect their families without early withdrawal penalties.
Life Insurance for Truck Drivers: How an Indexed Universal Life Policy Builds Wealth on the Road
Most people in corporate offices think of life insurance as a grim paperwork exercise that only pays out after you are gone. If you spend your weeks hauling freight across state lines, you know that traditional financial advice rarely fits your reality. Your income fluctuates with freight rates, fuel costs, and seasonal demand. When a transmission blows or downtime hits, a rigid retirement account locked behind early withdrawal penalties does not help you keep your wheels turning.
That is why a growing number of owner-operators and commercial drivers are looking at Indexed Universal Life insurance, commonly known as an IUL, as a practical business tool rather than just a safety net.
When structured properly, life insurance for truck drivers does two jobs at once. It protects your family with a tax-free death benefit while you are out on the highway, and it builds a living cash value account you can tap into while you are still alive. For drivers looking to scale their business, manage cash flow, and secure their future without begging a traditional bank for capital, understanding how an IUL works changes the entire game.
What Is an Indexed Universal Life (IUL) Policy?
An Indexed Universal Life policy is a form of permanent life insurance that combines lifelong coverage with a cash value growth component. Unlike term life insurance, which expires after 10, 20, or 30 years and leaves you with nothing if you outlive it, an IUL stays with you for life as long as the policy remains funded.
Here is how the mechanics work in plain terms:
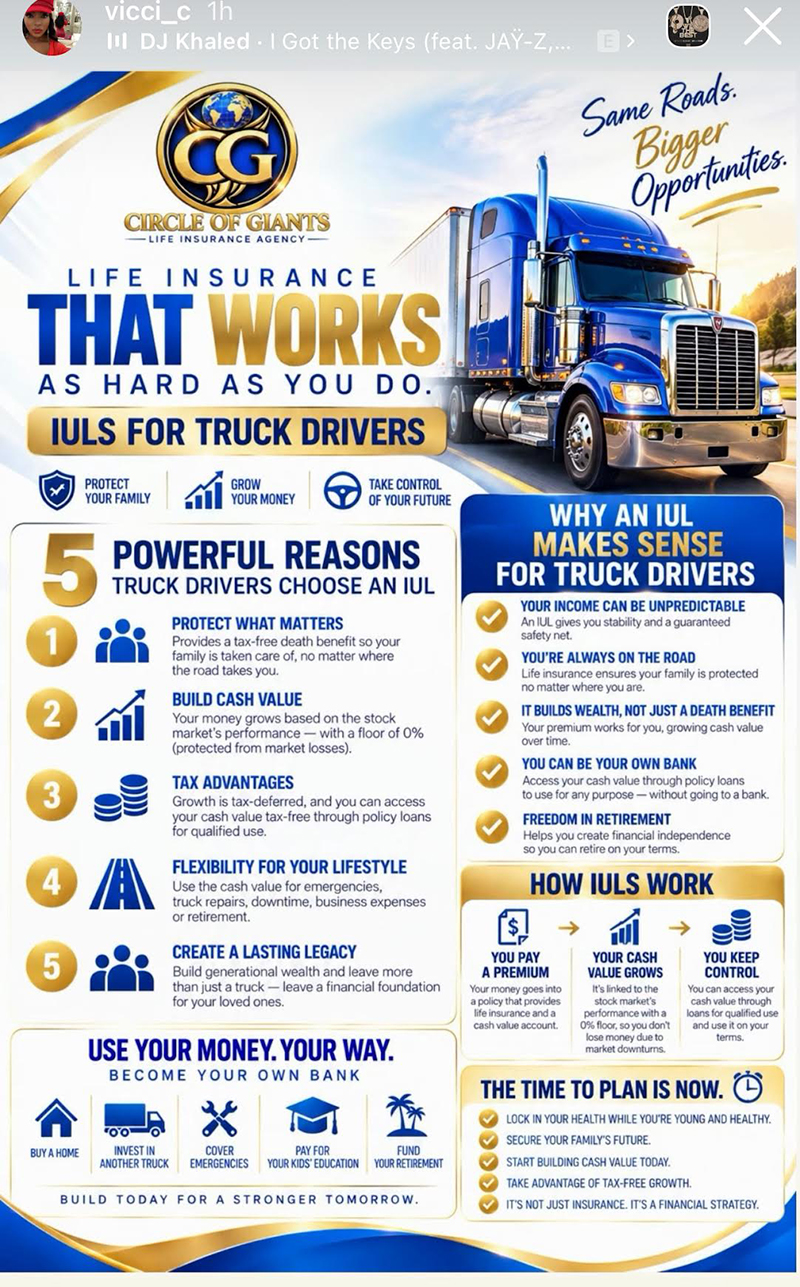
You pay your premium. A portion of your payment covers the cost of the insurance policy and administrative fees, while the remainder goes directly into your cash value account.
Your cash value grows with market protection. The money inside your cash value account earns interest linked to the performance of a stock market index, such as the S&P 500. Because your money is not directly invested in the stock market, your policy includes a floor, typically 0 percent. When the market booms, your cash value captures upside growth up to a set cap. When the market crashes, your account does not lose value due to market downturns.
You keep control of your capital. Over time, that cash value compounds on a tax-deferred basis. Once enough cash accumulates, you can access those funds through tax-free policy loans for qualified uses, essentially letting you act as your own bank.
For deeper regulatory context on how permanent cash value policies are structured and regulated, you can review the consumer guides published by the National Association of Insurance Commissioners.
Why Traditional Financial Advice Fails Commercial Drivers
If you run your own authority or work as an independent contractor, you already know that banks love steady W-2 paychecks and hate variable trucking income. Trying to get a fast business loan for an unexpected engine rebuild or a down payment on a second truck often means high interest rates, mountains of paperwork, or flat-out rejection.
Standard retirement vehicles like a 401(k) or traditional IRA come with their own set of roadblocks for drivers. Those accounts lock your capital away until age 59 and a half. If you need cash at age 42 to expand your fleet or survive a slow freight quarter, pulling money out triggers income taxes plus a 10 percent early withdrawal penalty from the Internal Revenue Service.
An IUL solves the liquidity problem. Because you are borrowing against your own accumulated cash value rather than taking a taxable distribution, you bypass credit checks, bank underwriting, and early withdrawal penalties.
5 Strategic Reasons Truck Drivers Use IULs for Business and Legacy
- Immediate Family Protection on High-Mileage Routes
Trucking remains one of the most demanding professions in the country. Having a permanent policy guarantees a tax-free death benefit for your spouse and children no matter where the road takes you. Your family will never have to scramble to cover a mortgage or funeral expenses if the unexpected happens. - Downside Market Protection with Upside Growth
Drivers deal with enough volatility in diesel prices and spot rates without worrying about Wall Street wiping out their savings. The 0 percent floor built into an IUL ensures that a bad year in the stock market never erases your previous gains.
- Tax-Advantaged Access to Capital
Under current federal tax rules, the cash value inside your life insurance policy grows tax-deferred. When you access that cash through structured policy loans, the money comes to you tax-free, provided the policy stays active and does not become a Modified Endowment Contract. You can learn more about how life insurance tax rules operate through the Insurance Information Institute.
- Real-World Flexibility for Trucking Expenses
You decide how to deploy your money. Drivers regularly use their policy cash value to cover sudden truck repairs, bridge income gaps during slow seasons, pay for their kids’ college tuition, buy a home, or purchase another rig to expand their operation.
- Building Generational Wealth Beyond the Truck
A semi-truck depreciates with every mile you put on the odometer. Leaving a used rig to your kids is not the same as leaving them a liquid financial foundation. An IUL lets you turn your hard-earned miles today into lasting generational wealth that transfers cleanly to your heirs.
How to Use Your Policy to Scale Your Trucking Business
Think of a properly funded IUL as a private reserve fund sitting right next to your business checking account. Instead of letting surplus revenue sit in a standard savings account earning next to nothing, you direct capital into your policy.
As your cash value builds, your money continues earning index-linked interest even while you borrow against it in many participating policy designs. When you spot a great deal on a used trailer or need capital to onboard a new driver, you request a loan from your insurance carrier. The funds hit your bank account in days. You pay the loan back on your own schedule as freight payments roll in, recapturing your liquidity for the next opportunity.
Frequently Asked Questions About IULs for Truckers
Can owner-operators qualify for an IUL with fluctuating income?
Yes. Insurance carriers look at your overall financial profile, net income, and health rather than requiring a rigid weekly W-2 paycheck. Flexible premium options also allow you to pay more during peak freight months and scale back to the minimum required premium during slower periods.
How quickly can I borrow money from my Indexed Universal Life policy?
Most policies require a few years of consistent funding before significant cash value becomes available to borrow, because early premiums go heavily toward policy setup and insurance costs. An IUL is a medium-to-long-term wealth strategy rather than an overnight checking account.
Does my job as a commercial truck driver increase my life insurance rates?
Commercial truck driving is generally viewed favorably by life insurance underwriters compared to extreme high-risk occupations. Your actual rate depends primarily on your age, overall health, driving record, and tobacco use, which is why locking in a policy while you are young and healthy saves substantial money over time.
#TruckingBusiness #OwnerOperator #IUL